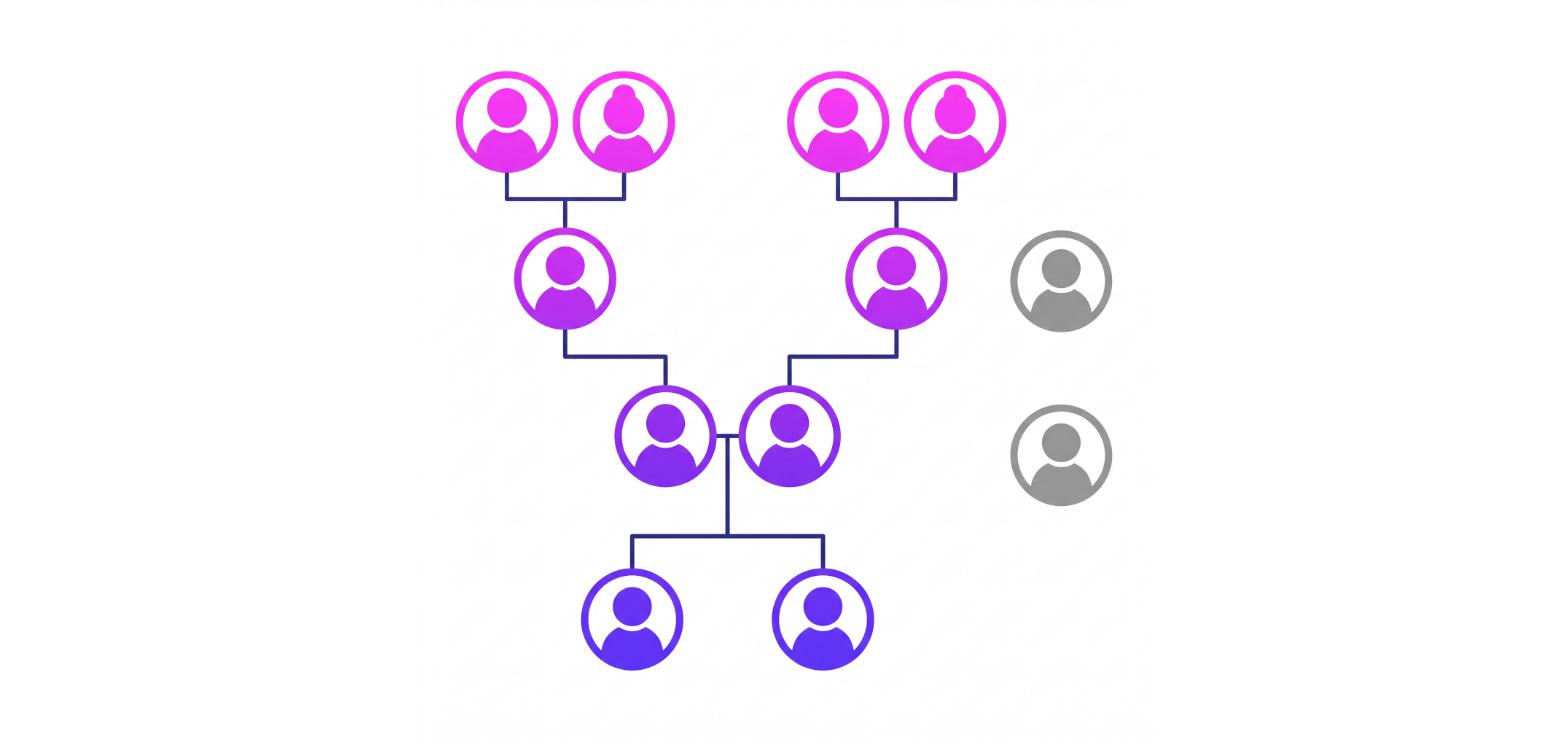
What if the gift is from a friend, cousin, or colleague?
Gifts from non-relatives are tax-free too — up to a point. If the total value of money (or property) you receive from all non-relatives in a financial year stays under ₹50,000, it’s exempt. Cross that threshold in aggregate, and the entire amount — not just the excess — becomes taxable as “income from other sources,” at your regular income tax slab rate.
So if a cousin gives you ₹30,000 for your birthday and a college friend adds another ₹25,000 later that year, you’ve crossed ₹50,000 in aggregate — and the full amount becomes taxable, not just the ₹5,000 over the line.
Gifts on your wedding are a separate exemption
Money and property you receive on the occasion of your own marriage are exempt from tax entirely, regardless of who gives it or how much it’s worth. This exemption is specific to the person getting married — it doesn’t extend to gifts given at a sibling’s or a friend’s wedding.
Property, not just cash, can trigger this rule
The same logic applies to property, not only money. If you receive immovable property — a flat or a plot of land — for free, or for a price well below its stamp duty value, the difference can be taxed as income, unless it comes from a relative, under a will, or through inheritance.
Inheritance and wills are always exempt
Anything you receive through inheritance or under a will falls outside the scope of this rule entirely, whoever it comes from. The same goes for gifts received “in contemplation of death” — a specific, narrower category under the law.
One thing couples often miss: gifting to a spouse isn’t the end of the story
Money you gift your spouse is tax-free for them to receive, as we’ve covered. But if they invest that money and it earns income — say, interest on a fixed deposit, or gains from a mutual fund — that income can get “clubbed” back into your own taxable income under separate clubbing provisions, rather than taxed in your spouse’s hands. It doesn’t undo the gift itself; it just means the tax department still looks at who the money originally came from when it comes to what that money then earns. This trips up dual-income couples more often than almost anything else in this article, simply because it isn’t intuitive.
A practical habit worth building: keep a paper trail
None of this requires a lawyer for routine family transfers. But if a gift is large, or comes from someone who isn’t technically a “relative” under the Act, it’s worth keeping basic proof on hand — a bank transfer record showing who sent it, and, for larger amounts, a simple gift deed stating it was given without consideration. It’s the kind of paperwork nobody thinks about until an assessing officer asks for it.
Quick answers
Is money from my father or mother taxable? No — parents are lineal ascendants, so any amount is exempt.
Can my grandparents gift me money tax-free? Yes, grandparents are covered as lineal ascendants too.
Is a gift from my father-in-law’s brother taxable? This one genuinely falls outside the “relative” list, so it’s governed by the ₹50,000 aggregate rule for non-relatives.
Do I need to declare tax-free gifts in my ITR? Gifts from relatives aren’t taxable, but large transactions can still show up in your Annual Information Statement (AIS) through bank reporting, so it’s worth being able to explain them if asked.
Is there a separate gift tax return to file? No separate “gift tax” return exists in India today. Taxable gifts, when they apply, are simply reported as income from other sources in your regular ITR.
This is general information, not tax or legal advice — everyone’s situation is different, and a chartered accountant can walk you through anything specific to your family. What’s rarely in dispute, though, is that most families lose track of who transferred what to whom over the years — which is exactly the kind of quiet mess an app like Famli, which brings your family’s bank accounts, SIPs, and FDs into one verified view, is built to help prevent.
This article is for general information only and does not constitute tax or legal advice. Please consult a qualified chartered accountant for guidance specific to your situation.
Investments are subject to market risks. Famli is a SEBI-registered Investment Adviser (INA000021979). Registration does not guarantee performance of advice or assurance of returns. Please read all scheme related documents carefully before investing.