
There isn’t a single right answer to “should I buy a house or invest in mutual funds” — and any article that gives you one is skipping the part where your situation matters more than the general rule. What follows is the actual decision: the factors that change the answer, and the questions worth asking before you commit either your down payment or your SIP amount to one path.
Why this question feels harder in 2026
For a lot of dual-income couples in their late 20s and 30s, this decision shows up around the same time: a stable job, a growing SIP portfolio, and parents or in-laws asking when the “own house” milestone is happening. Property prices in most metro and Tier-2 cities have kept climbing, home loan EMIs eat further into monthly cash flow than they did a decade ago, and mutual fund investing has become far more accessible through apps and SIPs. Both paths are more visible than they used to be — which is exactly why comparing them properly matters.
The two are not actually substitutes
The first thing to get right: a house and a mutual fund portfolio don’t serve the same purpose, so “which is better” is the wrong question. A house is a leveraged, illiquid, single-asset bet tied to one city and one property. A mutual fund portfolio is liquid, diversified across companies or bonds, and can be built up gradually. Comparing them as if they’re interchangeable options for the same goal is where most generic advice goes wrong.
A more useful way to frame it: a house is a lifestyle and stability decision with a financial dimension; a mutual fund portfolio is a financial goal decision with no lifestyle dimension. Once that’s separated, the comparison gets clearer.
Factors that actually change the answer
1. Liquidity
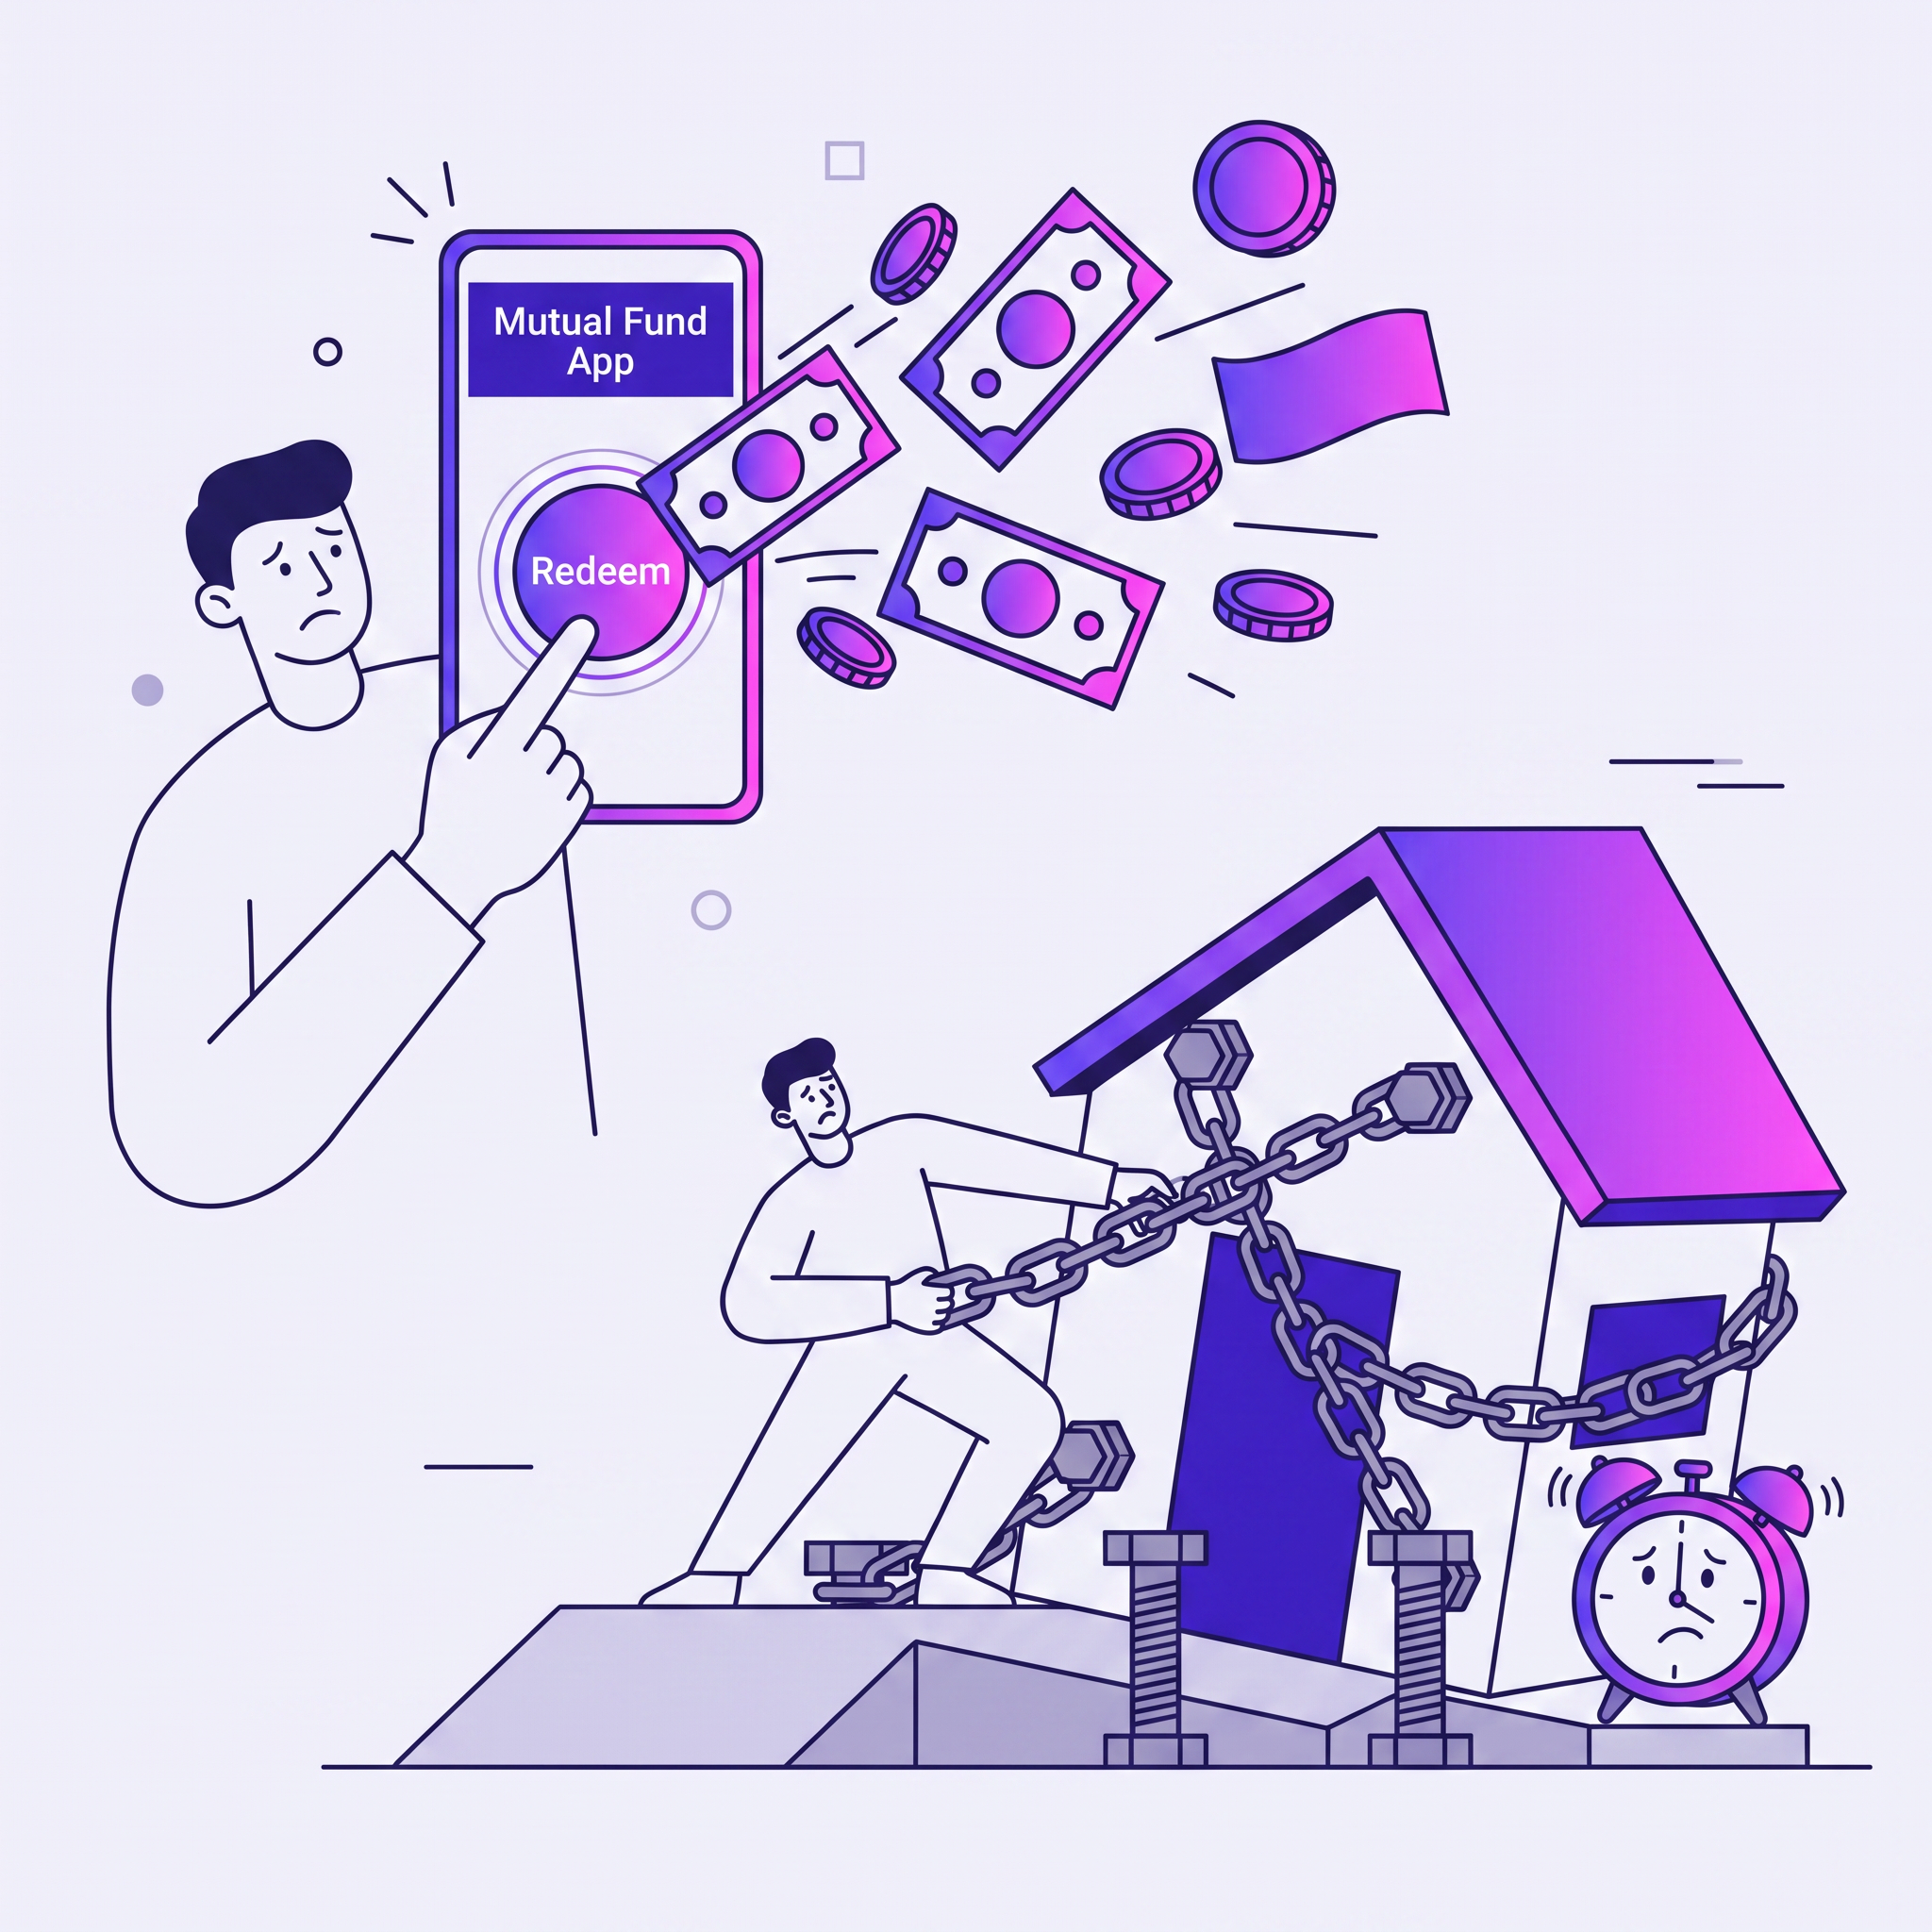
Mutual funds (outside of ELSS lock-ins) can typically be redeemed within a few working days. A house cannot be sold the minute one wants to and availability of cash is beyond the T+1 timeline for settlement of MFs. Also, a house cannot be partially sold — if you need ₹5 lakh urgently, you can’t sell a bedroom. For families without a strong emergency fund already in place, tying up savings in an illiquid asset adds risk, regardless of which asset it is.
2. Leverage and EMI commitment
A home loan lets you buy an asset worth several times your annual income, using the bank’s money. That leverage cuts both ways — it works in your favour if property values in your area rise, and against you if your income becomes unstable while the EMI is fixed. Mutual fund SIPs carry no such obligation; you can pause, reduce, or stop a SIP without a penalty or a bank calling you.
3. Cost of ownership beyond the purchase price
A house comes with stamp duty, registration, brokerage, interest cost over the loan tenure, society maintenance, property tax, and repairs. These are real, recurring costs that don’t show up in the headline property price. Mutual funds have expense ratios and exit loads, which are lower and more transparent by comparison, but the comparison should account for both sets of costs honestly rather than just the sticker price of the house.
4. Diversification
One house is one asset in one location. If that city’s property market underperforms, there’s no way to rebalance without selling the whole asset. A mutual fund portfolio, even a simple one, is spread across dozens or hundreds of companies or bonds, which reduces the impact of any single company or sector underperforming.
5. Tax treatment
Home loan interest and principal repayment both have tax benefits under specific sections of the Income Tax Act, subject to conditions and limits that change with the tax regime you choose. Equity mutual funds held over a year are taxed as long-term capital gains, with a separate set of rules. Neither is uniformly “more tax efficient” — it depends on your income slab, the tax regime you’re under, and how long you hold each.
6. Flexibility for life changes
Job relocations, family emergencies, career breaks — these are common in a 10–15 year window, which is roughly how long both a home loan and a long-term mutual fund goal tend to run. A house anchors you to a city. A mutual fund portfolio doesn’t.
Questions worth asking before either decision
- Is this house for living in, or as an investment? These have different answers. A house you’ll live in for 10+ years is a lifestyle decision where price appreciation is a bonus, not the point. A house bought purely as an investment should be compared against mutual funds on cost, liquidity, and diversification — and usually loses on at least two of the three.
- Do you already have 6 months of expenses set aside? If not, that comes before either a down payment or aggressive SIP increases.
- What’s your household’s combined EMI-to-income ratio going to be? Most lenders and financial planners treat anything above 40–50% of monthly income as a stretch, regardless of how good the property deal looks.
- Are you deciding this together, or is one partner driving it? Couples who’ve actually sat down with their combined net worth — not just individual bank balances — tend to make this call with fewer surprises later.
A reasonable way to think about it, not a rule
For most dual-income families, this isn’t a one-or-the-other decision at all. A common pattern: keep investing through SIPs for goals with a clear time horizon (retirement, children’s education), build the emergency fund first, and consider a home purchase when the EMI is comfortably affordable after those two are in place — not instead of them. Buying a house doesn’t have to mean stopping your SIPs, and continuing your SIPs doesn’t mean you’re avoiding the house question forever. The order matters more than the choice.
What actually helps here isn’t a verdict — it’s seeing your full financial picture in one place: SIPs across different apps, FDs across banks, an existing home loan if any, and what a new EMI would actually do to your monthly cash flow. Buddy, Famli’s AI assistant, can help pull that picture together so the EMI-vs-SIP math is based on your real numbers, not a rule of thumb.
FAQs
Is it better to buy a house or invest in mutual funds in India?
Neither is universally better — it depends on whether the house is for living in or as an investment, your existing emergency fund, your combined EMI-to-income ratio, and how many years you plan to stay in one city.
Can I do both — pay an EMI and continue SIPs?
Yes, and for most dual-income households this is the more common approach: SIPs continue for long-term goals while a portion of income goes toward an affordable EMI, rather than choosing one exclusively.
What percentage of income should go toward a home loan EMI?
Most lenders and financial planners treat 40–50% of monthly household income as an upper comfort limit for total EMI obligations, though this varies by lender and individual circumstances.
Is real estate more tax efficient than mutual funds?
Both have tax benefits under specific conditions — home loan interest and principal under applicable Income Tax Act sections, and equity mutual funds under long-term capital gains rules. Which is more efficient depends on your income slab, tax regime, and holding period, not a general rule.
Investments are subject to market risks. Famli is a SEBI-registered Investment Adviser (INA000021979). Registration does not guarantee performance of advice or assurance of returns. Please read all scheme-related documents carefully before investing. This article is for informational purposes and does not constitute personalised investment advice.