
Most Indian families can tell you roughly what they own — a home, a couple of SIPs, an FD or two, maybe a loan still running. Far fewer can tell you what it all adds up to. Not because the number is hard to find, but because it’s scattered across five apps, three banks, and one very old Excel sheet nobody’s opened since Diwali.
Net worth is the single number that answers “how are we actually doing, financially?” Here’s exactly how to calculate it, what to include if you’re an Indian household, and how often you should bother checking.
What Is Net Worth, and Why Does It Matter?
Net worth is the value of everything you own, minus everything you owe. It’s not your salary, and it’s not your savings account balance — it’s a snapshot of your total financial position at a point in time.
For a family, tracking net worth together matters more than tracking income alone, because two people can each feel like they’re “doing fine” individually while having no shared picture of where the household actually stands — what’s been saved, what’s still owed, and how close they are to a goal like a home down payment or their children’s education.
The Net Worth Formula
The formula is simple:
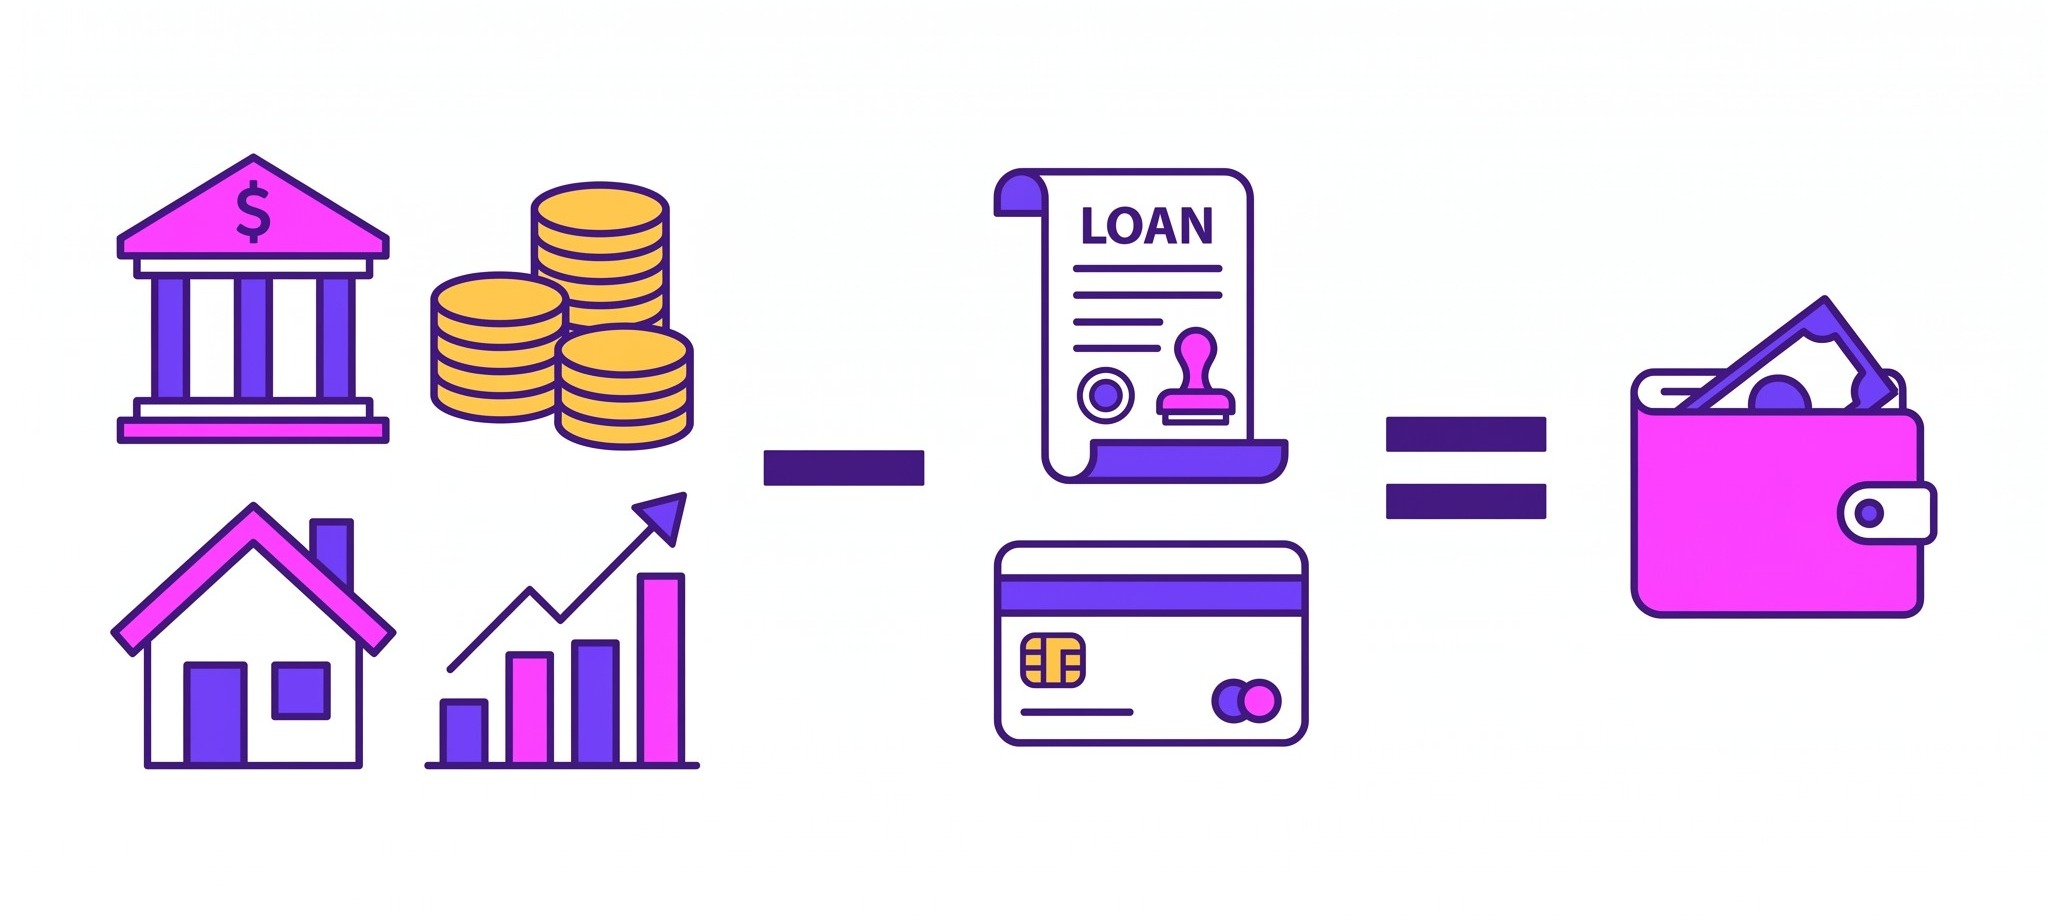
Net Worth = Total Assets − Total Liabilities
Assets are everything of value you own. Liabilities are everything you owe. Subtract one from the other, and you get your net worth. If assets exceed liabilities, your net worth is positive. If liabilities exceed assets, it’s negative — common for young households still paying off a home loan, and not something to panic over.
Step 1: List Your Assets
For an Indian household, assets typically fall into two buckets: financial and physical.
Financial assets — the ones you can usually value precisely and track digitally:
- Bank accounts (savings, current, joint accounts)
- Fixed deposits (FDs) across all banks
- Mutual fund and SIP holdings
- EPF, PPF, and NPS balances
- Direct equity holdings, if any
Physical assets — the ones that need periodic revaluation rather than daily tracking:
- Real estate (primary residence, land, any second property)
- Gold and jewellery
- Vehicles
It’s worth knowing where Indian household wealth actually sits before you start listing: RBI and NSS survey data consistently show that Indian households hold the large majority of their wealth in physical assets — real estate alone accounts for roughly three-quarters of household assets, with gold adding another meaningful share, and financial assets like deposits, mutual funds, and retirement accounts making up a comparatively small slice. That’s useful context — it means your real estate and gold valuations will likely move your net worth number more than any single SIP will, so don’t skip them just because they’re harder to look up.
Step 2: List Your Liabilities
Liabilities are anything you owe, regardless of size. The common ones for Indian households:
- Home loan (outstanding principal, not the original loan amount)
- Personal loans
- Auto loans
- Credit card balances carried month to month
- Education loans
- Any informal loans from family or friends, if you want a fully honest picture
A frequent mistake here is listing the original loan amount instead of the current outstanding balance. Always use the latest figure from your loan statement or lender app.
Step 3: Subtract and Interpret the Result
Once you have both totals:
Total Assets − Total Liabilities = Net Worth
A few notes on interpreting the number:
- A negative net worth in your late 20s or early 30s, usually driven by a home loan, is normal and not a red flag on its own — what matters is the trend over time.
- Net worth is a snapshot, not a forecast. It tells you where you stand today, not what you’ll have at retirement.
- Two households with the same net worth can have very different risk profiles — one might be almost entirely real estate, the other more liquid. The composition matters as much as the total.
How Often Should You Recalculate It?
There’s no single right answer, but a reasonable default for most families:
- Financial assets (bank balances, SIPs, FDs) — monthly or quarterly, since these change often and are easy to check.
- Physical assets (real estate, gold) — once or twice a year is enough, since these move slowly and don’t need frequent revaluation.
- After any major event — a home purchase, a large loan, an inheritance, or a job change — recalculate immediately rather than waiting for your usual cycle.
Checking too often can create anxiety over normal market fluctuations; checking too rarely means you lose the early-warning signal that net worth tracking is supposed to give you. Monthly-to-quarterly is the sweet spot most financial planners land on.
Why Couples and Families Should Track This Together
In most Indian households, financial responsibilities end up split — one person handles day-to-day expenses and bill payments, the other tracks investments, and parents often manage a separate set of FDs, property, or retirement savings on their own. Each person can have an accurate individual picture and the family can still be operating with zero shared visibility.
That gap shows up in ordinary conversations: one partner has SIPs running in one app, the other has FDs in a different bank, there’s a home loan with a third lender, and putting it all into one number means someone sitting down with statements from four or five places. It’s not that the information is missing — it’s that pulling it together takes real time, and even then, it usually lives in one person’s head or one spreadsheet that the rest of the family doesn’t see.
A shared, regularly updated net worth figure — even a rough one — gives a family a common starting point for bigger conversations: are we on track for a home down payment, how much of our wealth is genuinely liquid, and what happens if one income stops.
The Bottom Line
Calculating net worth isn’t complicated — it’s addition, subtraction, and a bit of digging to find current balances and outstanding loan figures. What makes it hard for most Indian families isn’t the math; it’s that the underlying accounts are scattered across banks, fund houses, and lenders, with nothing pulling the numbers into one place automatically.
If you’d rather not do this by hand every quarter, apps like Famli use India’s RBI-regulated Account Aggregator framework to pull your bank accounts, SIPs, FDs, and loans into a single, automatically updated dashboard — and let family members see the shared picture without anyone emailing a spreadsheet around.
Frequently asked questions
What counts as an asset when calculating net worth?
Anything of value you own: bank accounts, FDs, mutual funds and SIPs, EPF/PPF/NPS balances, direct equity, real estate, gold and jewellery, and vehicles. For Indian households, real estate and gold typically make up the largest share of total assets.
Should I use the original loan amount or the outstanding balance as a liability?
Always use the current outstanding balance from your latest loan statement, not the original loan amount. Using the original amount is one of the most common net worth calculation mistakes.
Is a negative net worth a bad sign?
Not necessarily. A negative net worth in your late 20s or early 30s, usually driven by a home loan, is common and not a red flag by itself — what matters is whether the trend is improving over time.
How often should I recalculate my family’s net worth?
Monthly or quarterly for financial assets like bank balances, SIPs, and FDs; once or twice a year for physical assets like real estate and gold, since these move slowly. Recalculate immediately after any major event such as a home purchase, large loan, or job change.
Famli is a SEBI-registered Investment Adviser (INA000021979). This article is for general information only and does not constitute investment advice.